

A Guide to Order Book Depth for Faster Trades
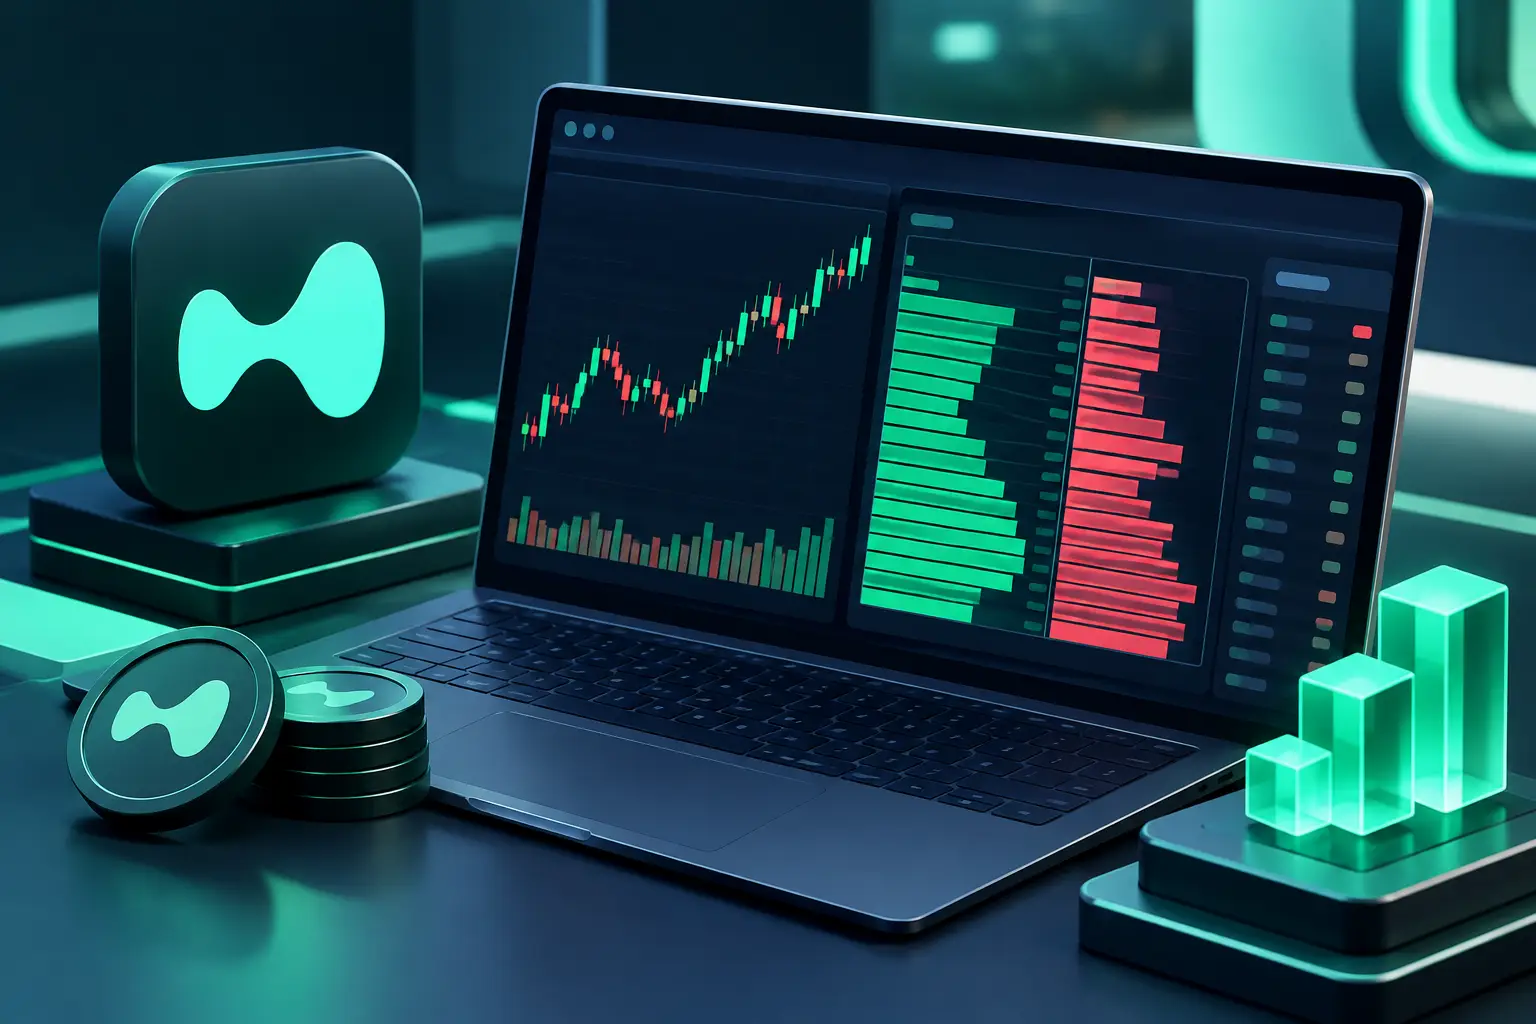
A trade can look clean on a chart and still produce a poor fill. The difference is often sitting one click away in the order book: the liquidity available between your intended entry and your actual execution. This guide to order book depth explains how to read that liquidity, judge whether it is likely to hold, and turn it into better order placement across perpetuals, spot, and fast-moving on-chain markets.
What order book depth actually measures
Order book depth is the quantity of resting buy and sell orders at different prices. Bids sit below the current market price. Asks sit above it. Together, they show the displayed liquidity that can absorb incoming market orders.
The best bid and best ask form the inside market. The gap between them is the spread. Depth begins immediately beyond that spread: how much size is available one tick away, two ticks away, and further from the current price.
For an active trader, depth is not a prediction tool in isolation. It is an execution map. It helps answer practical questions before you send an order: Can this position be entered without excessive slippage? Is there enough liquidity to scale out? Is a visible price level likely to slow the move, or is it too thin to matter?
A deep book has meaningful size distributed near the market on both sides. A thin book has little available size, wide gaps between levels, or liquidity concentrated far from the current price. Thin conditions make market orders expensive and stops more vulnerable to poor fills.
The three numbers that matter first
Start with the spread, the size at the best bid and ask, and cumulative depth over a realistic execution range. A one-tick spread is useful, but it does not guarantee capacity. If only a small amount is resting at the best ask, a larger buy order can immediately sweep several levels.
Cumulative depth is usually more useful than a single displayed level. If you intend to buy £20,000 worth of an asset, assess the offers required to fill approximately that size. The average price across those offers is closer to your likely market-order execution price than the last traded price shown on a chart.
Also compare the book to your own size. A position that is trivial in a major perpetual market may be large enough to move a smaller token, a tokenised equity market, or a prediction contract. There is no universal definition of good depth. It depends on the market, time of day, volatility, and order size.
Why order book depth changes your edge
Charts show where price traded. The book shows where orders are currently waiting. That distinction matters when timing entries, setting stops, and deploying systems that must act without hesitation.
Suppose price is approaching a visible ask wall. If substantial sell liquidity remains in place and trades repeatedly hit it without lifting it, the level may act as short-term resistance. But if aggressive buyers consume that liquidity and the wall does not replenish, the next available offers may be much higher. A breakout can accelerate simply because there is little inventory left to buy through.
The same logic applies to downside moves. When bids are sparse below a support level, a break may travel further than a chart-only setup suggests. During liquidation-driven moves in perpetuals, displayed depth can vanish quickly as participants cancel orders or risk systems force market execution. What looked liquid seconds earlier may no longer be executable at the same prices.
Depth therefore informs both opportunity and risk. It can help you identify a favourable entry, but its greater value is often preventing an order that has poor expected execution.
A guide to order book depth: read it in sequence
Do not begin by hunting for a single large order. Read the book as a changing structure.
1. Check the spread and immediate liquidity
A narrow spread and healthy size at the inside market usually support tighter execution. A widening spread signals uncertainty, lower participation, or a sudden imbalance in urgency. If the spread expands as price approaches your trigger, reconsider a market order or reduce size.
Watch whether best bid and ask size refresh after trades. Replenishment can indicate a participant willing to provide liquidity at that level. Conversely, a level that disappears when tested offers little support or resistance.
2. Measure the path to your fill
Estimate the price path required to fill your intended size. For a buy, add the available quantity at each ask level until you reach your target. For a sell, do the same through bids. The difference between the current mid-price and your estimated average fill is expected slippage before fees and funding.
This is where limit orders earn their place. A market order prioritises certainty of execution, not price. A limit order prioritises price, but may not fill. When the book is shallow, choosing between those two outcomes is a deliberate risk decision, not a minor order-entry setting.
3. Read imbalance carefully
Order book imbalance compares visible bid size with visible ask size over a chosen range. More bids than asks can signal near-term buying support; more asks than bids can signal supply overhead. It can also be meaningless if the size is far from the market or disappears as soon as price approaches.
Use imbalance as context alongside executed volume and price response. If bids outweigh asks but sellers continue to trade aggressively into those bids and price falls, the displayed demand is being absorbed. The market is telling you more through transactions than through resting orders.
4. Watch liquidity move, not just sit
Static snapshots are easy to misread. The useful information is how depth behaves as price moves. Are orders joining ahead of price, pulling away, or refreshing after fills? Does size repeatedly appear at one level and hold through pressure? Is the book becoming thinner in the direction of the move?
Fast order cancellation is normal in electronic markets. It is one reason a large displayed wall should never be treated as guaranteed liquidity. Some participants place and remove orders to manage exposure. Others may attempt to influence perception without intending to trade meaningful size. Treat visible depth as evidence, not a promise.
Turn depth into better order placement
For entries, match the order type to the book. Use a limit order when price discipline matters and a missed trade is acceptable. Use a marketable limit order when you need a fast fill but want a hard ceiling on a buy or floor on a sell. Reserve pure market orders for moments when execution certainty matters more than a few ticks, and only after checking the available depth.
For exits, depth should shape both position sizing and stop placement. A stop placed just beyond an obvious level in a thin book may trigger into a liquidity vacuum. That does not mean avoiding stops. It means sizing the trade so the likely worst-case fill remains tolerable, especially around news, funding events, market opens, or low-liquidity periods.
Scale execution when your order is material relative to nearby depth. Splitting a position can reduce immediate impact, although it introduces timing risk: the market may move before the full order completes. The correct approach depends on urgency. A mean-reversion entry near a stable level can tolerate patience. A momentum breakout often cannot.
Depth also improves take-profit decisions. If price is running into heavy displayed offers and aggressive buying is fading, taking partial profit may be rational. If offers are being consumed and liquidity above is sparse, exiting too early can be equally costly. The key is not to obey the book mechanically, but to assess whether it confirms or contradicts the trade premise.
Build order book depth into a systematic workflow
A discretionary read of depth is useful. A repeatable framework is better. Define the measurements that matter to your strategy before it goes live: maximum spread, minimum cumulative depth for a given notional size, maximum allowed estimated slippage, and conditions that block new entries.
For example, a short-term momentum system might only enter when the spread is within a defined limit, depth is not collapsing against the trade direction, and executed volume confirms the break. A passive mean-reversion system may instead require stable replenishment at its entry level and reject markets where cancellations are accelerating.
Then test the logic against realistic fills. Backtests based solely on candle closes can overstate performance for frequent strategies, especially in volatile or thin markets. Model fees, slippage, partial fills, and missed limits. If the edge disappears after conservative execution assumptions, it was not an executable edge.
Borsa gives strategy builders a direct path from TradingView-based analysis and Pine Script logic to live Hyperliquid execution. The useful standard is simple: define the execution rules, validate them on relevant historical conditions, then monitor whether live fills remain within the assumptions that made the strategy viable.
The mistakes that cost traders most
The first mistake is equating a large wall with certain support or resistance. Liquidity can be cancelled, moved, or consumed. The second is watching only displayed size while ignoring trades hitting the book. Aggressive flow reveals whether resting liquidity is holding.
The third is treating depth as identical across instruments. A highly liquid crypto perpetual, a tokenised commodity, and a macro outcome market can have entirely different trading characteristics. Recalibrate order size and execution rules for each market rather than carrying one threshold everywhere.
Finally, do not confuse tight spreads with low risk. A market can show an attractive inside price and still have very little depth beyond it. The cost appears only when your order reaches the next levels.
Read the book before you need it, not after a stop has slipped. When your order size, order type, and risk limits reflect the liquidity actually available, execution stops being an afterthought and becomes part of the strategy.